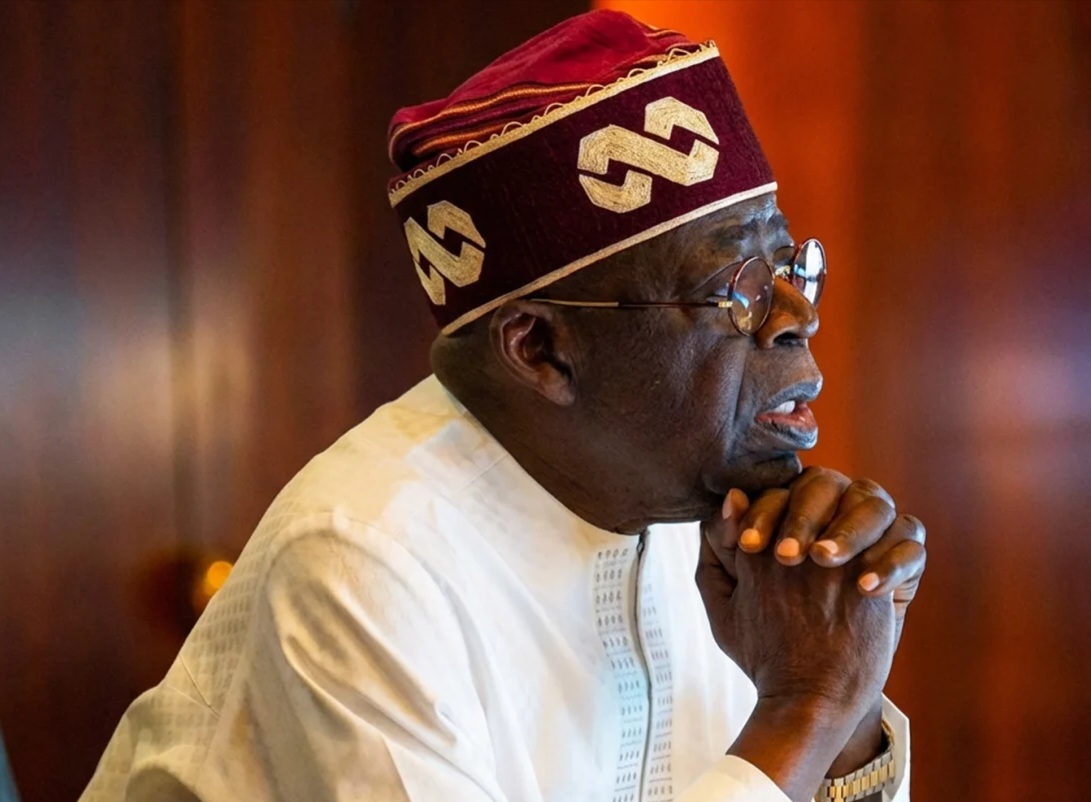
Nigerians seeking to own homes can now access mortgage loans of up to ₦100 million under a Federal Government-backed housing scheme introduced by President Bola Tinubu’s administration.
The facility, provided through the MOFI Real Estate Investment Fund (MREIF), offers qualified applicants loans at a fixed annual interest rate of 9.75 per cent, with repayment spread over a period of up to 20 years.
The initiative is aimed at making homeownership more affordable by allowing Nigerians to purchase residential properties without having to raise the full cost upfront.
Tinubu, while announcing the scheme, said applicants could secure mortgages with an initial contribution of just 10 per cent of the property’s value.
For instance, a Nigerian seeking to purchase a house worth ₦10 million would need to provide a deposit of ₦1 million, while the remaining ₦9 million would be financed through the mortgage.
The monthly repayment on such a loan would be approximately ₦85,400 over 20 years, according to the President’s illustration.
But how can interested Nigerians access the facility, and what are the requirements?
Here are the steps prospective homeowners are expected to follow.
CHECK IF YOU QUALIFY
Applicants must be Nigerian citizens and at least 21 years old.
They must also demonstrate sufficient income to repay the loan before attaining 60 years of age or the applicable retirement age.
Other requirements include meeting the scheme’s income and credit assessments and having the capacity to provide an initial contribution of at least 10 per cent of the property’s value.
Interested applicants can first use the affordability calculator on the MREIF housing portal to determine the mortgage amount they may qualify for.
VISIT THE OFFICIAL MORTGAGE PORTAL
Those interested in the scheme can begin their application through the MREIF website at www.mreif.com.ng or its housing pre-qualification portal at housing.mreif.com.ng/pre-qualifier.
The platform allows prospective applicants to provide information about their age, employment status, monthly earnings, proposed deposit and preferred repayment period.
The information will help determine whether they meet the initial requirements.
However, passing the pre-qualification stage does not automatically guarantee approval, as the participating bank will conduct further checks.
SELECT A HOUSE AND GATHER YOUR DOCUMENTS
Applicants are expected to identify a residential property they intend to purchase, either through the housing platform or independently.
The property must satisfy the fund’s requirements, including having acceptable title documents.
The documents applicants may be required to provide include:
- Valid means of identification.
- Employment offer or confirmation letter.
- Six months’ recent payslips for salaried workers.
- Recent utility bill.
- Birth certificate or declaration of age.
- Tax Clearance Certificate or tax card.
- Retirement Savings Account statement, where applicable.
- Property offer letter and title documents.
Participating banks may request additional documents, including bank statements and credit reports.
- SUBMIT YOUR MORTGAGE APPLICATION
After completing the pre-qualification process and identifying a suitable property, applicants can submit their applications alongside the required supporting documents through the designated MREIF channels.
The application will undergo verification, including checks on the applicant’s income, employment, credit history and ability to repay the loan.
The bank will also examine the property’s ownership documents and other relevant details before deciding whether to approve the mortgage.
- APPLY THROUGH A PARTICIPATING BANK
The MREIF scheme operates through commercial banks and mortgage institutions responsible for processing and administering the loans.
Participating institutions include Access Bank, FirstBank, FCMB, Globus Bank, Providus Bank, Stanbic IBTC Bank, Union Bank and Wema Bank.
Others are Abbey Mortgage Bank, AG Mortgage Bank, Federal Housing Authority Mortgage Bank, Gateway Mortgage Bank, Homebase Mortgage Bank, Imperial Homes Mortgage Bank, Infinity Trust Mortgage Bank, LivingTrust Mortgage Bank, LBIC Mortgage Bankers and Nigeria Police Mortgage Bank.
Applicants are advised to confirm that their preferred institution is currently processing MREIF mortgage applications.
The bank will assess the application, verify the applicant’s financial position, examine the property’s title and communicate its mortgage offer and applicable charges.
Successful applicants will then be required to pay their equity contribution and complete the necessary legal and insurance requirements before the loan is disbursed.
OTHER BENEFITS NIGERIANS SHOULD KNOW
Apart from the 10 per cent initial deposit, Tinubu said contributors to the Contributory Pension Scheme could use up to 25 per cent of their Retirement Savings Account funds towards their mortgage equity contribution, subject to the applicable conditions.
Married couples can also apply jointly, potentially increasing the amount they qualify to borrow by combining their incomes.
BEWARE: ₦100M LOAN IS NOT FREE MONEY
Despite the attractive terms, the facility is not a housing grant or free money from the Federal Government.
Beneficiaries are expected to repay the borrowed amount with the applicable interest and charges over the agreed period.
Prospective applicants should also be wary of fraudsters promising guaranteed approval in exchange for payments.
The safest approach is to use the official MREIF website and deal directly with recognised participating financial institutions.
For Nigerians struggling to raise the full cost of buying a house, the scheme offers an opportunity to spread the financial burden over several years rather than pay the entire amount upfront.
Don’t Miss Out! Join our WhatsApp Channel for instant news updates. Click here to join